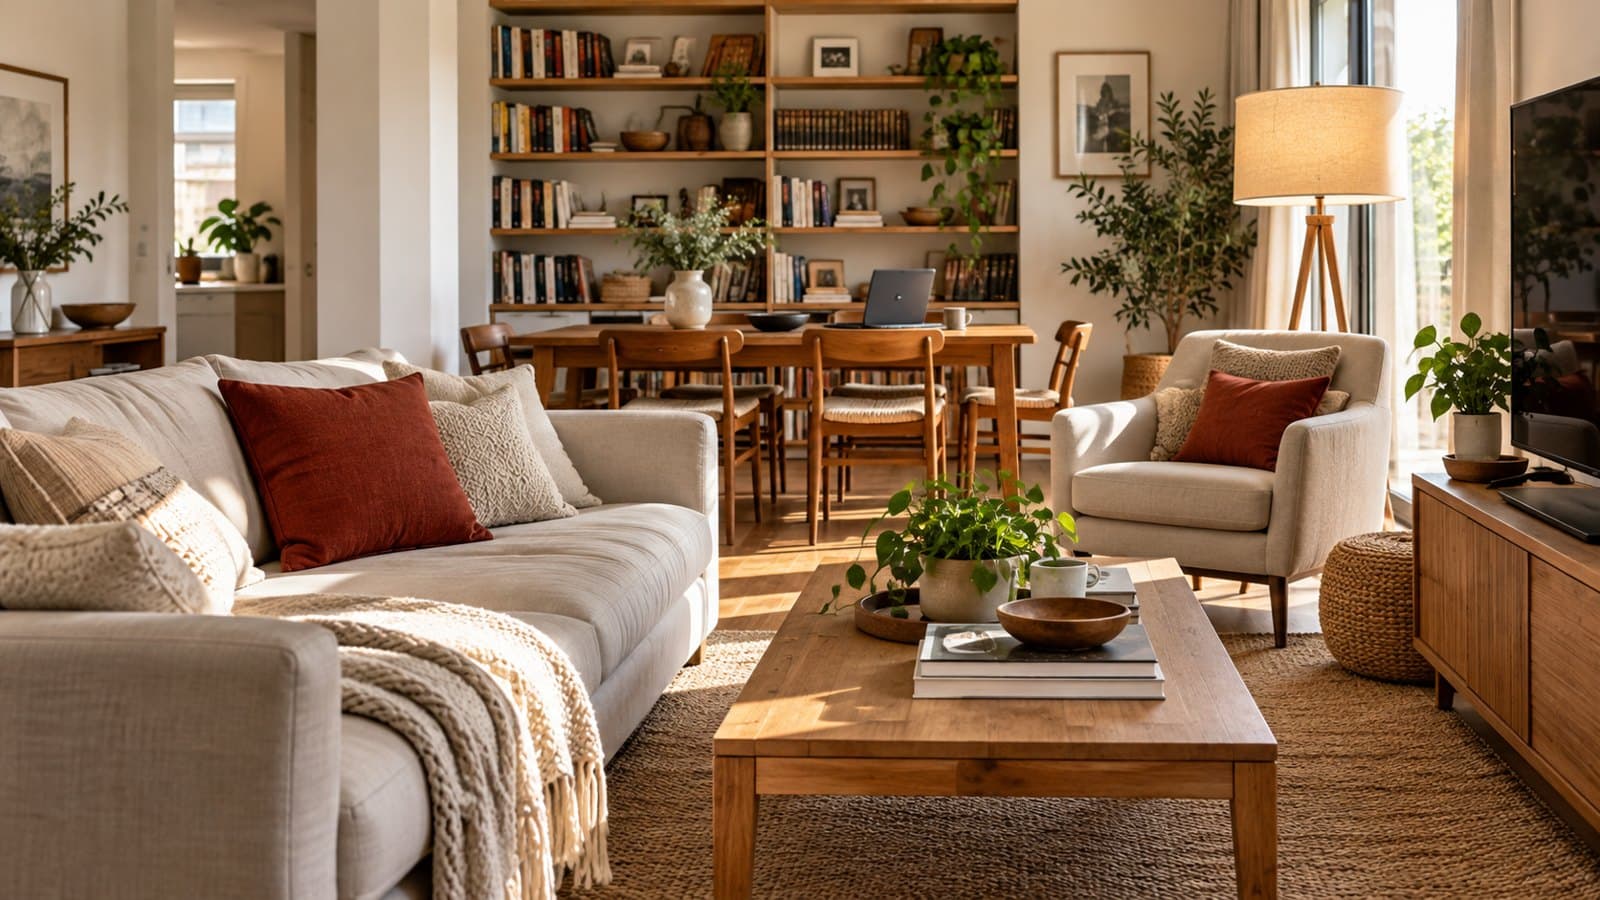
Insuring the home does not always mean insuring what is inside it. The building and contents are different insured items.
What counts as contents?
Generally, movable belongings inside the home: furniture, electrical and electronic appliances, clothes, household equipment and personal items. Elements permanently attached to the property may belong to the building instead. The policy definition determines the boundary.
A home accumulates value without you noticing
A fridge, television, bed, sofa, washing machine or a family's clothes may not seem like a large exposure individually. If they must all be replaced together, the picture changes.
Do not choose an amount approximately just to complete the application. Ask: if I lost a large part of my belongings, what would replacing them cost?
Estimate room by room
| Room | Items to consider |
|---|---|
| Living room | Sofa, table, television, lighting, furniture and electronics |
| Kitchen | Fridge, small appliances, utensils and movable equipment |
| Bedrooms | Beds, mattresses, furniture, clothes and personal items |
| Office or auxiliary spaces | Computer, equipment, tools and other belongings |
You do not need the price of every spoon. You do need a realistic total. Keep an inventory and useful supporting records; check how the insurer values replacement and evidence in a claim.
High-value items need a separate check
Jewellery, artworks, collections and other valuable belongings may have special limits, sublimits, conditions or a requirement for separate declaration and valuation.
If something would be expensive or difficult to replace, declare it and check the specific policy rather than assuming it is covered.
Contents is the item, not the event
First ask whether contents is insured. Then ask against which risks. Fire cover for contents does not automatically mean theft or earthquake cover too. Read the earthquake guide.
Owners and tenants can need different protection
An owner may want to protect both building and contents. A tenant may not need to insure the structure but may have significant belongings inside it. Start with what belongs to you and the financial loss if it is destroyed.
Review the amount periodically
New appliances, furniture, equipment, changes in household members or room use can change the total. An amount that once made sense may no longer reflect what is actually inside.
Remember: building and contents are different, the contents amount should be realistic, valuables need special checking, and the covered events matter as much as the insured items.